A stock-picking service can become part of the market it claims merely to observe—especially in thinly traded micro-caps. That does not make every recommendation dishonest, but it does mean subscribers must separate a good thesis from price action created by the recommendation itself.[1][2]
The Feedback Loop
Imagine a newsletter with 5,000 paying subscribers recommending a micro-cap that normally trades only a few thousand dollars’ worth of shares per day. If even a small fraction buys promptly, their combined market orders can consume the available offers and push the quoted price sharply higher.
That is not necessarily manipulation. It can be ordinary supply and demand meeting an unusually shallow order book. But the distinction matters: a price jump after publication may reveal more about the buying power of the audience than about a sudden improvement in the underlying business. The SEC notes that micro-caps are historically less liquid and more thinly traded, so purchases and sales can have an outsized impact on price.[1]
The service can then advertise the apparent success: “Our latest pick is up 30%.” New subscribers see a record of winners; existing subscribers feel validated; the next alert attracts even more buyers. The product’s perceived edge may partly be produced by its own distribution.
A Simple Illustration
Suppose a company has:
- A $40 million market capitalization
- A normal daily trading value of $15,000
- A wide bid-ask spread
- Limited shares actually offered for sale near the current price
A few hundred subscribers deploying $1,000 each represent $200,000 to $500,000 of sudden demand—many multiples of usual daily trading. The result can be a vertical chart that looks like discovery of value but may be closer to temporary scarcity.
The problem is asymmetric. Buying creates the exciting public signal: green candles, rising volume, screenshots, and testimonials. Selling is private, decentralized, and much harder. When enough holders later try to exit, the same lack of liquidity that amplified the advance can amplify the decline. The SEC specifically warns that low-liquidity micro-caps can be difficult to sell without noticeably affecting their price.[1]
Not Every Newsletter Is a Scam
It would be lazy—and wrong—to call every popular micro-cap analyst a fraud.
A serious analyst can uncover neglected businesses, explain a sound valuation case, identify governance improvements, or bring legitimate attention to a company that the market has overlooked. In that case, new demand may be a rational response to new analysis. Markets need research, disagreement, and investors willing to act on conclusions.
The stronger criticism is narrower:
- Subscribers should not confuse a recommendation-induced move with proof that the thesis was right.
- A self-fulfilling prophecy might still hurt you
- What was the stock’s normal dollar volume before the recommendation?
- How large is the recommended position relative to typical daily liquidity?
- Did the author, affiliates, or compensated parties own shares before publication?
- Can they trade immediately after publishing?
- Are all conflicts, compensation arrangements, and exits disclosed clearly?
- Does the thesis still work if the stock price does not rise for two years?
- Could a subscriber realistically build and exit a position without moving the market?
Regulators do not treat promotion itself as inherently improper, but they warn that paid promotions can be disguised as independent research and require disclosure of compensation in relevant cases.[2][3]
The Subscriber Problem
The business model can create a conflict even when the author is sincere.
The guru is rewarded for attention, subscriber growth, and visible wins. The subscriber is rewarded only if they buy at a sensible price, hold through uncertainty, and eventually sell into real liquidity. Those incentives overlap, but they are not identical.
Late subscribers often inherit the worst version of the trade:
- The thesis has already been publicized
- The initial demand has already lifted the price
- The risk/reward has changed
- The seller on the other side may be an earlier subscriber
- Exit liquidity may vanish exactly when confidence breaks
That is why a “track record” based on publication-date returns deserves skepticism. It may not reflect executable returns after spreads, slippage, position-size limits, and the practical difficulty of getting out. A service that publishes only winners, avoids marking positions to realistic exit prices, or refuses to discuss liquidity is selling a story, not an investment process.
Learn to Fish
The better product is not a slippery fish placed on your plate. It is a rod, a map, and a way to test whether the water is real.
Instead of asking, “What is the guru buying?” an investor should learn to ask:
- What does the business earn through a cycle?
- What is the balance-sheet risk?
- What is the downside if the thesis is wrong?
- What evidence would invalidate the thesis?
- What is a conservative estimate of intrinsic value?
- How much trading liquidity exists relative to my intended position?
- Am I buying a business—or chasing the last buyer?
That is the FatPitches angle: research should make the investor more independent, not more dependent on the next alert.
A useful stock idea should leave the reader with a written thesis, valuation range, downside case, key risks, and a position-sizing rule. If the original author disappeared tomorrow, the investor should still know why they own the stock, what would make them sell, and what evidence would prove them wrong.
Bear Markets Expose It
The feedback loop is most fragile in a correction or bear market.
In a rising market, buyers are plentiful, speculative capital is abundant, and a newsletter alert can meet an eager audience. In a falling market, the audience may already be fully invested, new subscriptions can slow, and buyers become more selective. The self-reinforcing mechanism reverses.
- Fewer new buyers arrive after the alert
- Existing subscribers face losses elsewhere and need cash
- Stops, margin calls, and fear increase sell pressure
- Wide spreads widen further
- The price declines, creating ugly public “track records”
- Redemptions and cancellations remove another source of future demand
Then the earlier rise gets reinterpreted. What looked like market validation may have been a fragile chain of incremental buyers. Once that chain breaks, the stock must stand on cash flows, assets, governance, and genuine long-term demand.
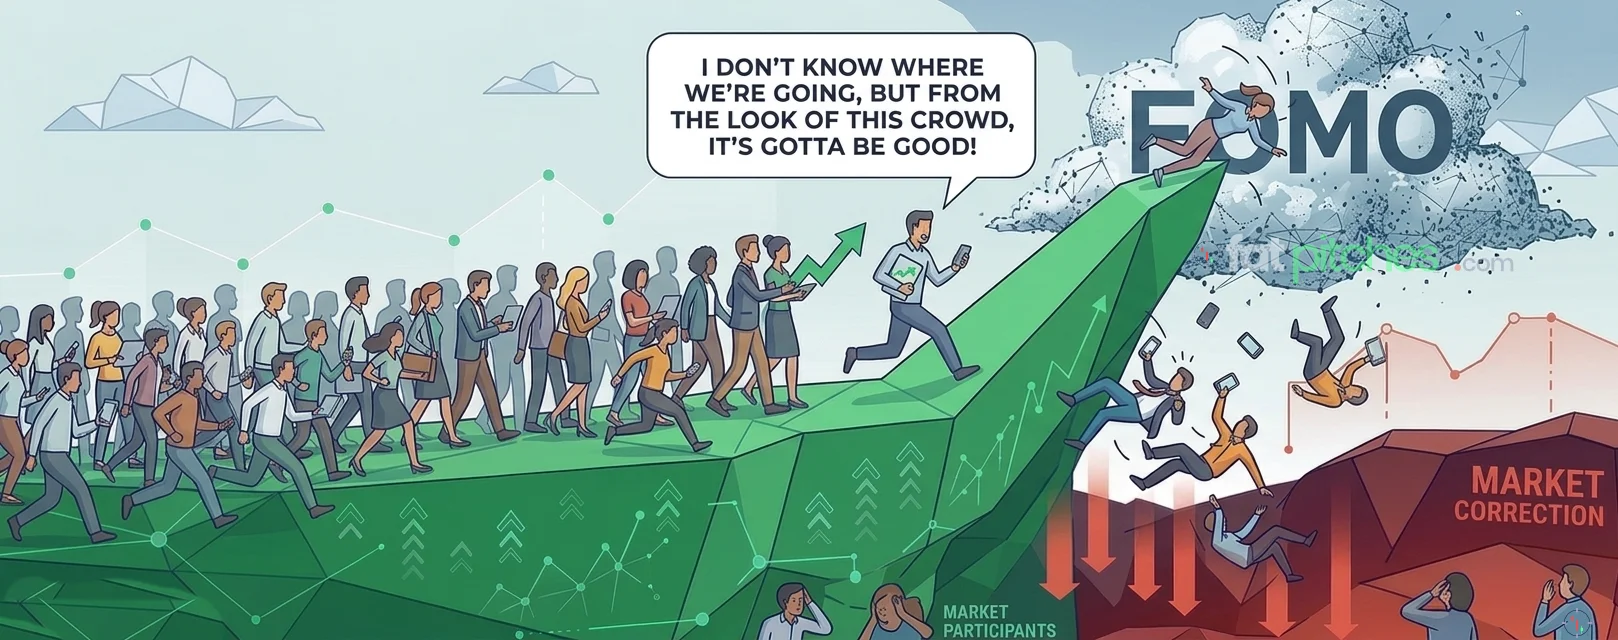
Micro-caps have historically been more volatile than larger stocks, and their lower liquidity makes sudden price movements—and difficult exits—more likely. In a correction, that is not a footnote. It becomes the central risk.[1]
A Better Standard
The standard should not be “Did the pick go up after publication?”
It should be:
Would this still be an attractive investment if nobody knew the guru had recommended it?
If the answer is yes, the research may have uncovered something valuable. If the answer is no—if the return depends on a fresh wave of subscribers, social-media attention, or an ever-rising price—then the investor is not analyzing a business. They are financing a distribution loop.
FatPitches stands firmly on the other side of that divide: not “follow this person,” but understand the business, inspect the incentives, measure liquidity, define downside, and make the decision your own.
That is slower than copying a ticker. It is also far more likely to survive the day the easy buyers disappear. And more importantly, it would help you learn and feel better with yourself, specially during a correction or a down market since you made your own decision.
FatPitches is built to help you build the opposite habit: learn to fish for yourself. Build your own thesis, test your own assumptions, challenge them, remember always invert, and keep your dry powder ready across more qualified opportunities—so you are not dependent on somebody else’s next alert. One bankroll. More rods in the water.
“Fish where the fish are” -Charlie Munger
Your judgment still decides where to cast.
Sources [1] Investor Bulletin: Microcap Stock Basics (Part 3 of 3: Risk) https://www.investor.gov/introduction-investing/general-resources/news-alerts/alerts-bulletins/investor-bulletins/investor-2
[2] Microcap Stock: A Guide for Investors - SEC.gov https://www.sec.gov/about/reports-publications/investorpubsmicrocapstock
[3] Updated Investor Alert: Fraudulent Stock Promotions https://www.sec.gov/oiea/investor-alerts-bulletins/ia_promotions.html
[4] Beware of Stock Recommendations on Investment Research Websites https://www.investor.gov/introduction-investing/general-resources/news-alerts/alerts-bulletins/investor-alerts/investor-41
[5] Microcap Fraud | Investor.gov https://www.investor.gov/additional-resources/spotlight/microcap-fraud
[6] Michael Hall, et al. https://www.sec.gov/enforcement-litigation/litigation-releases/lr-15901
[7] Anthony J. Thompson, Jr., Jay Fung, and Eric Van Nguyen https://www.sec.gov/enforcement-litigation/litigation-releases/lr-23137
[8] SEC Crackdown On ‘Net Scams - CBS News https://www.cbsnews.com/news/sec-crackdown-on-net-scams/
[9] SEC charges 44 with Net fraud https://www.zdnet.com/article/sec-charges-44-with-net-fraud/
[10] Microcap Stocks: A Double-edged Sword https://www.napa-net.org/news/2019/2/microcap-stocks-double-edged-sword/
[11] Official SEC SealSEC https://www.sec.gov/investor/alerts/socialmediaandfraud.pdf
[12] SEC Scrutinizes “Fake News” Stock Promotion Schemes https://www.zuckermanlaw.com/sec-whistleblower-lawyers/sec-scrutinizes-fake-news-promoting-stocks/
[13] Regulatory Notice 21-03 | FINRA.org https://www.finra.org/rules-guidance/notices/21-03
[14] Pump and Dump Schemes - Investor.gov https://www.investor.gov/protect-your-investments/fraud/types-fraud/pump-and-dump-schemes
[15] SEC Issues White Paper on Penny Stock Risks https://www.huffpost.com/entry/sec-issues-white-paper-on-penny-stock-risks_b_58f0ef54e4b04cae050dc6a4